Investment Considerations: PizzaExpress £70m super senior term loan


Social distancing and government policies in response to COVID-19 have led to the temporary closures or scaling back of customer facing businesses globally. In the face of limited or no trading, company executives have been quick to shore up liquidity through operational (cutting costs, limiting capex), sociopolitical (lobbying for/exploring government support) and financial (rights issues, postponing liability management, drawing down on RCFs, seeking new debt facilities) measures.
While typically stressed or more leveraged names would have difficulty accessing new money in the debt markets, idiosyncratic opportunities yet exist for opportunistic lenders to place super senior/senior secured facilities through baskets in borrower's existing facility documentation. As compensation for the increased COVID-related risk, these lenders would naturally require enhanced economics. One recent precedent is HPS Investment Partners' recently announced £70m super senior secured term facility to the troubled PizzaExpress. Our analysis of the commercial and financial considerations of the transaction is summarized below.

Background
As at Q319, PizzaExpress operated a chain of 482 stores in the UK and Ireland and 153 in 14 international markets (primarily in China). The entity is majority owned by Hony capital, a Chinese large-cap private equity firm backed by large Chinese, European and US institutional investors. The company's performance and liquidity has declined in recent years due to increased competition, rising labour and property inputs as well as high debt costs resulting from their bond-financed international expansion. A summary of the Group's current and pro forma capital structure is tabled below:

As a result of these operational and capital structure issues, the Company's SSNs and SUNs have been trading at distressed levels (63.5 and 40.0p on the £ respectively as at April 2, 2020) the former of which matures in August 2021. The Group's trading outlook and liquidity issues are now exacerbated by the recent COVID-19 measures with the company closing all its European locations since late March in accordance with state requirements/guidelines. Although the company still offers "cook at home" products through large grocery retailers, this represents an immaterial amount of trading revenue. With a Q3 2019 cash balance of £20.4m,and Q3 2020 maturities of £30m in super senior facilities, new money was required to cover future CAPEX and its £48m semi-annual bond interest payment due in Q1 2020.
The bond Indentures (debt basket summary below) allows the Company the contractual flexibility to secure super senior debt. Although last year the Sponsor purchased £80m (40%) of the SUNs at discounted price as price, Hony chose to allow a third party to provide the needed liquidity on a super senior basis, foregoing the opportunity to have the strongest position in any likely future restructuring. Potential reasons for this shift in strategy will be ventilated in a future Unitranche memo.
Debt basket summary: 2021 SSNs and 2022 SUNs
Additional Permitted Debt: Issuer and restricted subs FCCR >= 2.0x and Senior Secured Leverage <= 4.5x.
Permitted Debt Carve-Outs:
Credit Facilities basket: MAX (£70m,75% of EBITDA);
General Debt basket: MAX (£30m, (8% total assets);
Capital lease obligations basket: MAX (£20m, 5% of total assets);
Debt to finance Chinese call option: GBP 70m;
Unlimited securitisations
Source: Debtwire
Please see pro forma Org Chart below outlining the various existing and proposed facilities (as at March 31, 2020):

Transaction Overview
Lender: Funds managed by HPS Investment Partners
Borrower: PizzaExpress Financing 2 plc
Guarantors: PizzaExpress Financing 1 plc (parent) and restricted group subsidiaries
Amount: £70m
Type: Term loan (non-revolving)
Purpose: Working capital/Refinancing
Tenor: 3 years from disbursement
Pricing: LIBOR +6.75% subject to 0.75% floor
OID: 2.5%
Warrants: Unknown
Ranking/security: Super Senior Secured charge over material European subsidiaries
Covenants: Minimum EBITDA of £40m; Springing maturity
Sources and Uses

Company Snapshot
Ownership: Sponsor-owned (Hony Capital
Industry: Casual Dining
Primary markets: UK & Ireland - 482; International (China, Hong Kong, UAE) -153
LTM Sales (Q3 2019): £552m
Market Share: ~9% (UK full-service branded restaurants)
Seasonality: Low
LTM EBITDA (Q3 2019): £76m
Main products: Fast casual pizza and other Italian-inspired fare
Channels: Dine-in: (97%), delivery (2%), dough products (0.8%) franchise (0.2%)
Strategy: Value-oriented
Employees: >14,000

External Analysis
Macro Level

Industry Level (Porter's 5 Forces)

Market Overview/Outlook
PizzaExpress operates in the full-service branded restaurant market.
Market Size: £5.94bn 2018 (UK & Ireland)
Market CAGR: 3.3% (2018-2021)
Competitors: Immediate competitors - Domino's, Papa Johns, Pizza Hut, Franc Manca -
Source: MCA UK Restaurant Market Report, September 2018
Historical and Future Trading

Historical
As at the time of publication, the latest financials available were for the 39 weeks ended September 29, 2019 ("9M 2019").
Group revenue increased by 2.1% during the the 9ME 2019, with LFL growth or 0.5% (0.2% decline in GBP terms). The growth was primarily due to the four net new site openings in UK & Ireland and 5.5% LFL sales growth in the International segment, despite unrest in Hong Kong. UK & Ireland LFL sales were however down 0.5% as a result of continued low consumer confidence stemming from Brexit concerns. FY18 group LFL sales declined by 2% due to increased competition in China and low consumer confidence/"extreme" weather in the domestic market.
Group GPM for the 9M 2019 (21.3%) declined from the FY18 level of 22.7% due to increased (4-5% y-oy) living wage and property costs which management chose to not pass on the the consumer in order to drive volume post Brexit. Group GPM for FY18 was 23.1%, a reduction from 25.6% in FY17 as a result of the aforementioned cost pressures. As a value player, Pizza Express margins are also lower than many of its more differentiated competitors.
Operating expenses as a % of Sales remained flat highlighting good control of group overhead costs. Group EBITDA in the 9M 2019 was £52.0m, representing a decline of of £4.6m (8.1%) mainly due to the weak performance in the UK/Ireland (£4m EBITDA decline). The EBITDA margin therefore declined by 140bps to 12.7% due to the increased direct costs. Group EBITDA margin in FY18 also declined by 2.9%.
£38.0m in operating cash flow (before finance costs) was generated during the 9ME 2019 after a £10.2m working capital use of cash primarily driven by a decrease in payables. EBITDA to operating cash flow conversion for the period was however a robust 73%.
After £17.1m in capex during the 9M 2019, representing an £18.9m reduction from the previous period, £21m in FCF was available for debt servicing. 58% of 9ME 19 CAPEX was for maintenance purposes.
After £48.4m in bond payments, closing cash reduced by £27.2m to a low of £20.4m prompting the Q4 2019 drawdown of the £20m SS RCF and the £10m SS loan from Hony.
Unitranche Projections
Many companies have withheld or withdrawn guidance as result of the unprecedented market outlook. However, to determine whether the HPS funding and maintenance covenants provides adequate headroom/contractual protections, Unitranche has prepared illustrative "do nothing" case projections (i.e. no debt restructuring) for the period FY19 - FY23 assuming the following:
No opening of new stores post Q1 2020
Quarterly revenue as percentage of the Q3 2019 level as follows: 100% (Q4 2019 & Q1 2020) 0% (Q2 2020), 50% (Q3 2020), 75% (Q4 2020) and 100% (Q1 2021 onwards)
Fixed quarterly direct costs for store leases and overheads of £21.9m
Variable quarterly direct costs a percentage of sales of 29% (food), 29% (labour) and 2.5% (variable store overheads)
Group overheads as a percentage of the Q3 2019 level as follows: 100% (Q4 2019 & Q1 2020) 80% (Q2 2020), 85% (Q3 2020) 75% (Q4 2020) and 100% (Q1 2021 onwards)
Only maintenance CAPEX for the forecast period
HPS debt is fully drawn in early Q2 2020 and interest paid quarterly
Refinancing of SSNs and SUNs (illustrative - highly unlikely without prior debt restructuring)
Please note that the following were not modelled:
Additional equity injections
Additional debt
Working capital liquidity levers (supplier stretching etc)
Liability management
Intra-quarter cash movements
The Unitranche credit metrics summary is summarized in the table below.
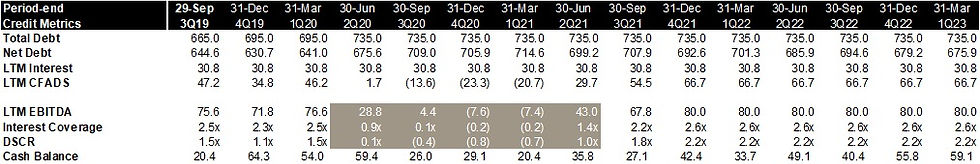
Excluding, Q2 2020 to Q2 2021, where waivers would likely be granted or covenants not tested, the following credit metrics were observed:
Minimum LTM EBITDA : £67.8m in Q2 2021, indicating that there is perhaps too much headroom in the maintenance EBITDA covenant
Minimum LTM DSCR: 1.1x in Q4 1209, indicating the Group will have adequate funds to service the HPS and bond interest payments
Minimum Cash Balance: £27.1m in Q3 2021, indicating that the HPS debt provides adequate liquidity should trading pick up as projected
Under a sensitized scenario of 2 successive quarters (Q2 2020 and Q3 2020) of full shutdown (i.e. 0% revenue earned) it was observed that, absent the addition of additional liquidity, the Company would run out of cash in Q3 2020
Exit/Returns
Going Concern Scenarios:
Refinancing/Restructuring
Sale
Both scenarios would likely result in repayment at par, given HPS' super senior status. In both cases a going concern valuation would be the basis, where HPS' minimum EBITDA covenant of £40m serves as the floor. A distressed EBITDA multiple of 5x provides an exit valuation of £200m, guaranteeing full recovery of the super senior debt as per the waterfall below. The senior secured debt naturally reduces the recovery of the SSN and SUN holders, who have been primed.

Returns
The table below summarizes the returns over the life of the loan. A minimum unlevered IRR of 8.3% is expected at maturity 3 which increases to 26.0 % in year 1 partly due to the make-whole mechanism. HPS's IRRs will probably be higher than illustrated as the lender would most likely use leverage.

Liquidation Scenario:
According to Unitrache's conservative liquidation analysis, over £250m in net proceeds would be realized from liquidation of the £1,190.1m in assets available as per the Q3 19 balance sheet, thus securing full recovery of the super senior debt.

Sources: Debtwire, Capital structure, Company disclosures

Comments